
Hyderabad has emerged as India’s leading office market in the third quarter of 2026 according to CBRE’s latest data, recording about 5.3 million sq. ft. of office absorption during the July-September period.
That put Hyderabad ahead of Bengaluru, which recorded around 4.9 million sq. ft., and Delhi-NCR at about 4.4 million sq. ft. Together, the three cities accounted for nearly 69 per cent of India’s quarterly office leasing activity.
India as a whole recorded around 21 million sq. ft. of office absorption in Q3 2026, up 6 per cent year-on-year. Hyderabad therefore accounted for roughly one-fourth of the total activity during the quarter.
The bigger story, however, is Hyderabad’s growing strength as a Global Capability Centre destination.
According to CBRE, GCCs leased about 8.7 million sq. ft. of office space across India during Q3. Hyderabad accounted for 37 per cent of that demand, ahead of Bengaluru at 28 per cent.
Chennai and Delhi-NCR each contributed 11 per cent, while Pune and Mumbai accounted for smaller shares.
That means Hyderabad was not just strong in overall leasing during the quarter but also led the country in one of the most closely watched segments of the commercial real-estate market.
GCCs have become a major engine of India’s office sector as global companies expand functions such as technology, engineering, analytics, finance, research and product development in the country.
CBRE said GCCs accounted for around 41 per cent of total office take-up in Q3 and 42 per cent during the first nine months of 2026.
Hyderabad’s availability of new Grade-A office space is also playing a role.
The city led new office supply during the quarter, with CBRE data showing approximately 10.2 million sq. ft. of completions. Bengaluru followed with about 3.9 million sq. ft. and Pune with 2.7 million sq. ft.
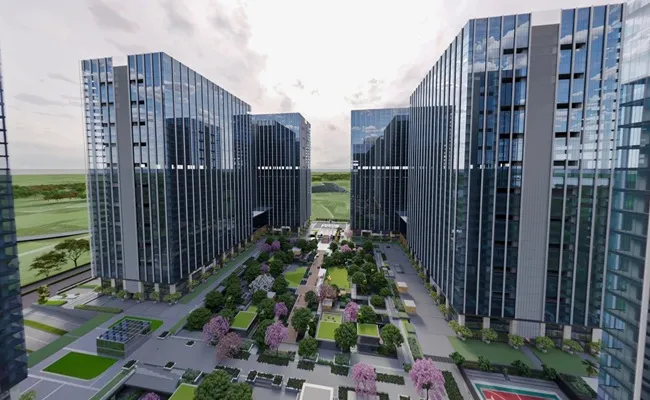
Large corporate transactions have also added visibility to Hyderabad’s office market, particularly across Madhapur, HITEC City, Financial District and nearby business corridors.
Premium developments are attracting global financial services, technology and GCC occupiers looking for large, modern campuses.
The broader trend is supported by the increasing importance of Bengaluru and Hyderabad in India’s GCC ecosystem.
Colliers estimates that the two cities together have accounted for more than 60 per cent of GCC office leasing since 2021.
However, describing Hyderabad as India’s undisputed No. 1 office market requires some context.
Different property consultancies use different definitions of leasing and absorption.
Colliers, for example, reported Bengaluru as the leading office market in Q3 2026 under its Grade-A gross absorption methodology, with 5.2 million sq. ft., while Hyderabad recorded 2.2 million sq. ft. under the same framework.
So, Hyderabad’s No. 1 position applies specifically to CBRE’s Q3 2026 office absorption data rather than every industry measurement.
Even with that qualification, the underlying trend is clear. Hyderabad is attracting significant corporate expansion, adding large amounts of premium office supply and taking an increasingly important share of India’s GCC demand.
For the city, the challenge will now be to ensure that rapid office development is matched by infrastructure, transport connectivity, housing and talent availability.
But Q3 2026 has given Hyderabad another strong marker of how quickly its commercial real-estate and GCC ecosystem is expanding.