

So, August 2026 finally was the first time in the Indian automobile market’s timeline when “alternative” energy four-wheelers outsold petrol ones. Interesting statistic. But as all statistics are, each can have multiple interpretations and implications.
Here I am sharing my interpretation, as someone who has worked in the industry and keenly observe trends and behavioural patterns.
So, lets see the numbers first. In August 2026, “alternative” energy vehicles were 41.95% of total 4-wheeler sales, just over “pure” petrol ones at 40.85%. These alternate energies are made up of 25.28% of CNG / LPG, 9.04% of strong hybrids and 7.63% of electric vehicles. Diesel, as an alternative to petrol remained more or less stable at 17.21% of the overall monthly sales.
If we see a 3-year trend, comparing the Augusts of 2024 and 2026, pure petrol has primarily lost out to CNG / LPG, the former dropping from 52.00% in share to 40.85% while the latter shot up from 18.72% to 25.28%. While strong hybrids remained flat, electrics did move up from 2.12% to 7.63%, but on a very small base. Interestingly, while many have wishes diesel away, its share has dropped from 18.40% to 17.21%. All this is on a movement of total retail sales from 320,291 units to 402,398 units, a 16% year on year increase!
Why has this happened? Is this a clear trend? What are the implications for the automakers? Will the entire market follow this trend, if there is one at all?
India is a very unique marketplace. It is much more mature than many of us actually admit. And it is multi-faceted. While there are key common behavioural undercurrents, the diversity in decision making makes it fun for the analyst and frustrating for the marketer.
Economy above all
Given that an automobile is still a huge investment for an average buyer, economy of operation becomes a key factor when choosing a particular brand, a particular body style and also a particular energy type. After all, the government still considers a car as a luxury item, even though it has reduced GST on a certain category. A truly progressive policy maker would have reduced the GST on the sub 4-metre automobile to a mere 5% and watched the market literally explode. Mind you, the Auto Mission Plan 2016 had predicted a 6.00 million passenger car market in FY 2026. We were a million and a half short, largely led by the policy maker’s inability to let go of the short term returns in favour of the long term benefits of a uniformly lower taxation.
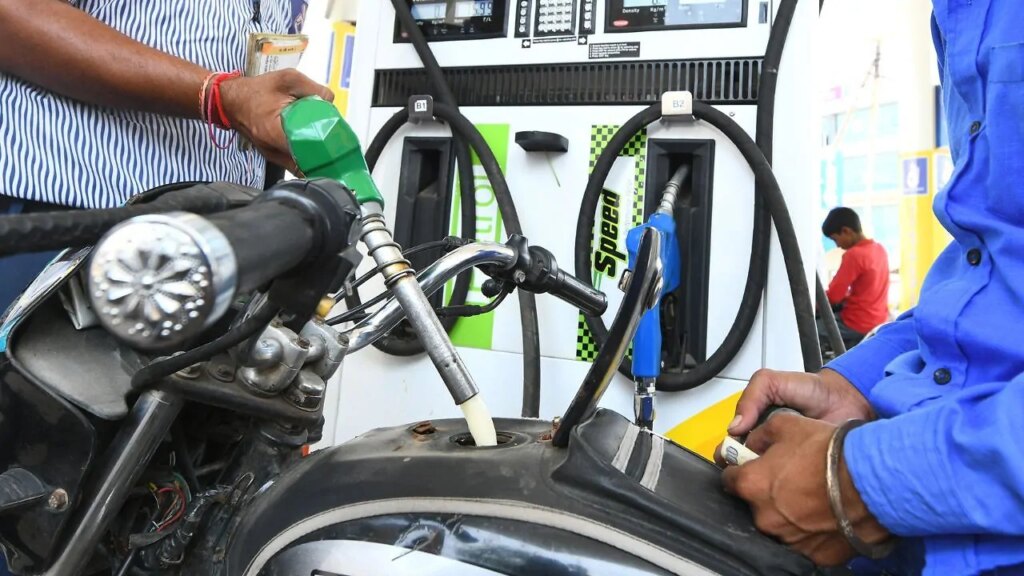
Hence, an average buyer will choose energy options that ensure economy of operation. CNG / LPG does that in good measure, given the rise in dispensing stations over the last 3 years. The vehicle owner is ready to be in a queue for hours to fill up, given the huge savings in running the vehicle. Also, a large part of the CNG / LPG vehicle buyers are independent and fleet taxi operators.
Electric gives the same benefit of savings over time, especially for taxis and heavy users. BaaS as a solution also helps bring the initial buying price down.
It must be noted that the much “written off” diesel option has actually grown from 59,930 units in August 2024 to 69,252 units in August 2026, a good 15% growth, albeit in the above 4-metre SUV body style segment.
Ethanol embroglio
The E20 debate has been a messy one, with conflicting opinion and views going out, making the traditional petrol vehicle buyer either decide to wait and watch or switch to a ‘safer’ alternative like CNG if in immediate need of a vehicle. The sheer lack of transparency, from all quarters, on what exactly happens to the fuel efficiency in an E20 compliant vehicle has not helped matters at all.
The ones with money, typically upgrading or buying their second vehicle, typically opt for a strong hybrid. This is a higher investment and there are not too many options available right now to see a higher rate of adoption. This is why this category has grown from 28,820 units in August 2024 to only 36,376 units in August 2026, a rise of only 7550 units, in spite of a very compelling benefit proposition.
Constraint of choice
This is a factor many automakers do not wish to talk about – the fact that mainstream brands like Maruti Suzuki have simply decided to move away from diesel while other automakers like a Tata or Mahindra or Renault or Hyundai refuse to offer a value-packed entry-level diesel hatchback. The greed for more profits per unit sold have made brands deliberately starve the entry level band of Rs.3.00-5.00 lakhs, forcing the first time buyer to either upgrade to a higher price band or go for a used vehicle. The paradox is that in spite of a multitude of choice for those with money, the entry level buyer of first time upgrader from a two-wheeler has very little to choose from.
Trend-worthy?
So, will the trend of CNG / LPG and electric alternatives to the petrol continue and bring about a significant shift in consumer choice and behaviour? Unless brands like Maruti Suzuki, Tata and Hyundai revive the entry-level petrol hatchback / crossover segment, this trend will become more pronounced. CNG will become the smarter alternative to pure petrol. Electric will make sense only for heavy individual users and institutions and fleets. Strong hybrids will rule the roost in more expensive vehicles, unless a mainstream automaker wishes to disrupt the lower end market with an affordable strong hybrid. And do not ever rule out diesel. It will become cleaner and leaner and possibly in bio-diesel form, challenging the strong hybrid and even the higher segment electric.
One trend is as clear as a foggy winter morning in Delhi – India will never choose just one way to drive. It is too complex and mature for that to ever happen. And the market is large enough to allow each energy form to grow stronger and offer itself as a better alternative, leaner, cleaner and ‘cooler’.